Insurance & Claims Help

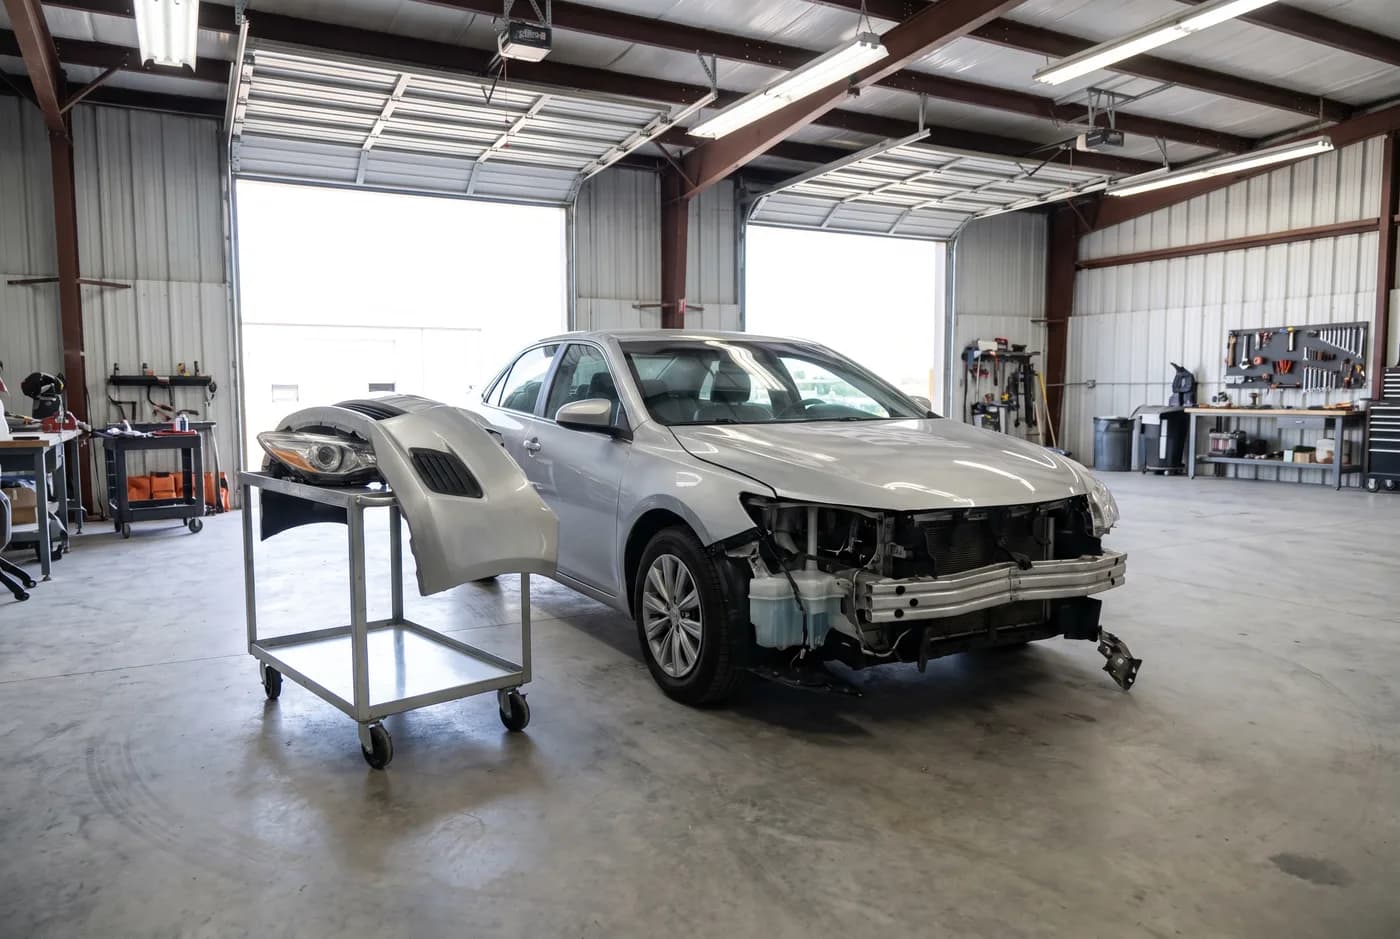
Dealing with an insurance claim after an accident can be overwhelming. We help manage the insurance claim process, communicate with the insurance company, and handle supplements when additional damage is found.

We handle the insurance side for you

You don't have to play middleman between a body shop and an adjuster. We document the damage, write the estimate, submit it to your insurance company, and file a supplement if we find more once the repair is underway. We work with every insurer, so it doesn't matter whose name is on your policy. Your job is to approve the plan and drive away in a repaired car. Ours is everything in between.

You choose your repair shop, not your insurance company

This is the part many drivers don't realize, so it's worth saying plainly: where your vehicle gets repaired is your decision. In Kansas, your insurer can suggest a shop from its network, but it cannot require you to use one, and your coverage is the same wherever you go.

Insurers sometimes steer drivers toward network shops because those shops agree to the insurer's pricing and turnaround targets. That can be efficient, and it can also put pressure on a repair. When you bring your car to us, your claim is paid the same way, and the repair team answers to you. If an adjuster tells you that you *have* to use a particular shop, it’s worth knowing that you have the right to choose.
How a collision insurance claim works

Most claims follow the same path:

  1. 1

    Report the claim.

    Call your insurer and get a claim number. You can do this before or after you choose your shop.

  2. 2

    Get an estimate.

    Bring the car to us or send photos. In most cases you don't need to gather three estimates first.

  3. 3

    We work with your adjuster.

    We document the damage, send the estimate, and handle the back-and-forth.

  4. 4

    The insurer approves the work.

    Once the estimate is agreed, the repair is authorized.

  5. 5

    We disassemble and file any supplement.

    If we find hidden damage once the car is apart, we get it approved before the added work begins (more on supplements below).

  6. 6

    We complete the repair.

    Bodywork, paint, reassembly, calibration, and a quality check.

  7. 7

    The insurer pays, you pay your deductible.

    The insurer covers the approved repair, and you cover your deductible drop-off.

What a supplement is

A supplement is an addition to the original estimate. Once repairs begin and the vehicle is disassembled, we often uncover hidden damage that wasn’t visible during the initial inspection. We document it and submit it to your insurer for approval before that work goes ahead. Supplements are a normal part of most collision repairs, not a sign that anything went wrong.

Your deductible

Your deductible is the share of the repair you agreed to pay when you bought your policy. If you file a claim on your own coverage, it applies regardless of who caused the accident. We'll tell you the amount up front so there are no surprises. Be cautious of any shop that promises to waive or “cover” your deductible. Depending on how it’s handled, that can violate insurance laws or your policy terms and may put your claim at risk.

OEM and aftermarket parts

Insurance estimates don't always call for original-equipment parts. Some policies and approvals specify aftermarket or recycled parts to control cost. We'll tell you what your insurer has approved, explain the difference, and push for the parts your vehicle needs for a safe, correct repair, using original-equipment parts when the repair and your coverage allow. You always have the right to ask about the parts used for the repair of your car.

If your vehicle is a total loss

Sometimes the cost to repair a vehicle is close to or more than what the vehicle is worth. When that happens, the insurer declares it a total loss and pays you its value rather than paying for the repair. If your car reaches that point, we'll help you understand the assessment and your options. If you believe the offered value is low, you can question it, and documentation of your vehicle's condition and history helps.

The accident wasn't your fault?

You have two options. You can file through the other driver's insurance, or you can file on your own policy and let your insurer recover from theirs, which is often faster. Either way, we work with whichever company is handling the claim and keep the repair moving while the fault question gets sorted out.

What to look at next:

  • Auto collision repair and the rest of our services
  • Get a free estimate
I-CAR Gold ClassGM CertifiedToyota CertifiedKia CertifiedHyundai CertifiedChrysler CertifiedBBB A+ Rated

FAQ

No. The choice of repair shop is yours. In Kansas, your insurer can suggest a shop from its network, but it cannot require you to use one, and your coverage is the same either way. Choosing your own shop does not slow your claim or cost you more. We work with every insurance company.

Yes, all of them. We document the damage, send the estimate to your insurer, communicate directly with the adjuster, and file any supplements. You don't have to manage the calls and paperwork yourself. Whose name is on your policy doesn't change how we handle your repair.

Usually not. The idea that you must collect three estimates is a common myth. In most cases you can bring your vehicle straight to the shop you've chosen, and we work out the estimate with your insurer from there. Check your policy if you're unsure.

A supplement is an addition to the first estimate. When we disassemble the vehicle, we often find damage that wasn't visible at the preliminary inspection. We document it and submit it to your insurer for approval before doing that work. It's a routine part of most repairs, not a sign of a problem.

Yes. Your deductible is the share you agreed to pay in your policy, and it applies regardless of fault if you file on your own coverage.

It depends on your policy and the approval. Some estimates call for aftermarket or recycled parts to control cost. We tell you what your insurer approved, explain the options, and advocate for the parts your vehicle needs for a safe repair, using original-equipment parts when the repair and your coverage allow.

If the cost to repair your vehicle is close to or more than its value, the insurer declares a total loss and pays you the vehicle's worth instead of repairing it. We'll help you understand the assessment. If the offered value seems low, you can question it, and records of your vehicle's condition help your case.

You can file through the other driver's insurer, or file on your own policy and let your insurer recover the cost from theirs, which is often quicker. We work with whichever company handles the claim and keep your repair moving while fault is determined.

Let us take the claim off your plate

Send a few photos for a free estimate and we'll handle the insurance side from there. Or call and we'll explain your options before you commit to anything.

Get an Estimate Call 620-663-8742